The Least Saturated Markets for Contractors, Measured Across 100 Metros
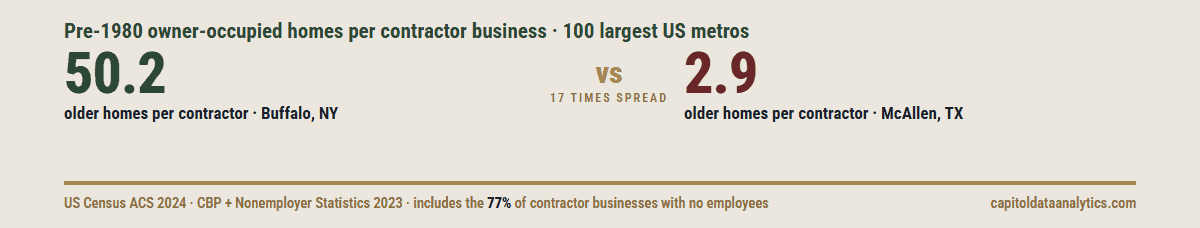
The least saturated markets for contractors are mostly the older housing metros of the Northeast and Midwest. Across the 100 largest US metros, Buffalo has 50.2 owner-occupied homes built before 1980 for every contractor business, and McAllen, Texas has 2.9, a spread of 17 times. The most crowded quarter is 20 Southern metros and 5 Western ones.
Those numbers come from the Home Improvement Opportunity Gap, an index CDA built from public Census data: owner-occupied homes built before 1980, divided by specialty trade contractor businesses, including those with no employees. It is an index built from housing stock, not a measure of dollars spent, and it describes competition, not whether a market is a good place to run a business. Explore the full interactive index or download the CSV.
Where is home improvement demand highest relative to competition?
Measured as older homes per contractor business, it is highest in the Northeast and Midwest and lowest in the South. The median Northeastern metro in the index has 26.9 owner-occupied homes built before 1980 for each contractor business. The median Midwestern metro has 21.8, the median Western metro 18.8, and the median Southern metro 11.4.
The index sorts the 100 largest metros into four tiers of 25. It uses tiers rather than a numbered list because most neighboring metros in a straight list are statistically indistinguishable: the gap between one metro and the next is usually inside the survey’s margin of error.
| Tier | Older homes per contractor business | Example metros (alphabetical) | Where the tier sits |
|---|---|---|---|
| Least crowded | 23.1 to 50.2 | Buffalo, Chicago, Cleveland, Detroit, Honolulu, New York, Philadelphia, Pittsburgh, San Francisco, San Jose | 19 of 25 in the Northeast and Midwest |
| Below average crowding | 17.2 to 22.7 | Boston, Cincinnati, Indianapolis, Kansas City, Los Angeles, Minneapolis, Sacramento, San Diego, Seattle | 10 of 25 in the West |
| Above average crowding | 11.3 to 17.0 | Columbus, Denver, Memphis, Oklahoma City, Richmond, Salt Lake City, Tampa, Washington | 17 of 25 in the South |
| Most crowded | 2.9 to 11.2 | Atlanta, Austin, Dallas, Houston, Las Vegas, McAllen, Miami, Nashville, Orlando, Phoenix, Raleigh | 20 of 25 in the South, the other 5 in the West |
Two metros stand clear of the pack. Buffalo is the highest of the 100, and not narrowly: no other large metro comes within 14 older homes per contractor of it. McAllen is the lowest, at 2.9. Metros near a tier boundary could reasonably sit in the tier next door, which is why the index shows a margin of error for every metro.
Why are Southern metros the most crowded for contractors?
The most crowded metros have young homes and large contractor fields, and the index rewards the opposite of both. In the most crowded tier, the median share of owner-occupied homes built before 1980 is 27%, and the median density is 347 contractor businesses per 10,000 owner-occupied homes. In the least crowded tier, those medians are 65% and 209.
Housing age does much of the work. In Austin, Raleigh, Orlando, and Cape Coral, fewer than one in four owner-occupied homes predates 1980. Older homes need more repair and replacement work, and these metros simply have fewer of them for each contractor to serve.
Contractor density does the rest. Miami has 649 contractor businesses per 10,000 owner-occupied homes, the densest field of the 100. Buffalo has 152, the thinnest. That is a 4.3 times difference in how many businesses compete for the same number of homes.
It is worth checking which half drives a given metro. Las Vegas lands in the most crowded tier even though it has about 202 contractor businesses per 10,000 owner-occupied homes, a thinner field than the typical metro in the least crowded tier. It lands there because only 15% of its owner-occupied homes predate 1980. If your work does not depend on the age of the house, the density figure is the one to watch.
Metro size is not the explanation. Among the 100 largest metros, population has no relationship to the index: the rank correlation is +0.02, where 0 means no relationship and 1 means the two orderings match exactly. New York and Chicago sit in the least crowded tier, while Dallas, Houston, Atlanta, and Miami sit in the most crowded. Across all 924 metro and micropolitan areas we computed, there is a weak negative relationship (−0.14): smaller markets tend to be slightly less crowded.
What are the two kinds of underserved market, and which fits your business?
The least crowded tier holds two very different markets. One is older, modestly priced metros such as Buffalo and Pittsburgh. The other is expensive coastal metros such as San Jose, San Francisco, and Honolulu. Both combine old housing with thin contractor fields, but the homes in them are worth very different amounts.
| Metro | Owner-occupied homes built before 1980 | Contractor businesses per 10,000 owner-occupied homes | Median home value |
|---|---|---|---|
| Buffalo, NY | 76% | 152 | $226,100 |
| Pittsburgh, PA | 72% | 209 | $215,000 |
| San Jose, CA | 65% | 185 | $1,447,800 |
| San Francisco, CA | 68% | 195 | $1,140,700 |
| Honolulu, HI | 57% | 182 | $897,500 |
That difference matters for what kind of work each market supports. Harvard’s Joint Center for Housing Studies has found that local home improvement spending tracks median home values, so the same count of older homes can carry very different revenue. The first profile is many older homes at modest values, where pricing has to fit local incomes: it suits a shop built on volume and modest tickets. The second is older homes worth four to more than six times as much: it suits a shop built on fewer, larger projects.
We checked whether weighting the index by home value or household income would change the picture. The overall pattern holds, but the top changes: under either weighting, San Jose and San Francisco move to the very top of the index. Both weighted versions are in the downloadable data. The two profiles are a pattern in the data. We did not establish why the coastal metros have thin contractor fields, and we do not speculate on it.
Neither profile is a reason to move. They describe how much competition exists for work on older homes, which is one input into where to expand, open a second location, or point an acquisition budget.
Why is counting contractors harder than it looks?
Counting contractors is hard because most contractor businesses have no employees. Businesses with no employees, most of them sole proprietors, make up 77% of specialty trade contractor businesses in the median large metro, and 79% nationally. The Census Bureau counts them in Nonemployer Statistics, not in County Business Patterns, so a ranking built on employer counts alone leaves out roughly three of every four contractor businesses.
The share also varies by market. In McAllen, 96% of contractor businesses have no employees; in Seattle, 58%. An employer count would understate McAllen’s field far more than Seattle’s, which distorts any comparison between them.
Businesses are not workers, either. A business count treats a sole proprietor and a firm with 200 technicians as one each. We tested that by rebuilding the index on a rough worker count (employees, plus one for each business with no employees). The shape held: a 0.89 correlation with the published index, Buffalo still the highest, and Austin, Cape Coral, Las Vegas, Provo, and Raleigh still at the crowded end. The Census Bureau adds noise to employment figures to protect privacy, so we treat that version as a directional check, not a second index.
A crowded market is not a bad market. It is a market where the same work is harder to win.
How do you read your own market with the same method?
Divide the number of owner-occupied homes built before 1980 by the number of specialty trade contractor businesses, including those with no employees. If your metro is one of the 100 largest, look it up in the index first. For a county, a smaller metro, or a single trade, every input is free from the Census Bureau.
- Count the older homes. On data.census.gov, open American Community Survey table B25036 (tenure by year structure built), five year estimates, for your metro or county. Add the owner-occupied rows for 1970 to 1979, 1960 to 1969, 1950 to 1959, 1940 to 1949, and 1939 or earlier.
- Count the employer contractors. In County Business Patterns, pull the number of establishments for NAICS 238, specialty trade contractors, for the same area.
- Count the businesses with no employees. In Nonemployer Statistics, pull establishments for NAICS 238. These are mostly sole proprietors, and skipping this step leaves out about three quarters of the field.
- Divide. Older homes divided by the sum of steps 2 and 3. Among the 100 largest metros, a result below about 11 falls in the most crowded quarter, and above about 23 in the least crowded.
- Check which half drives it. Divide all contractor businesses by all owner-occupied homes (the owner-occupied total at the top of the same B25036 table) and multiply by 10,000. Compare the result with Buffalo’s 152 and Miami’s 649 to see whether your number comes from housing age or from competition.
- Narrow it to your trade. For plumbing and HVAC, use NAICS 238220 in County Business Patterns and 23822 in Nonemployer Statistics. For electrical, use 238210 and 23821. The two sources label the same industries with different code lengths. A single trade gives a much larger number than all trades combined, so compare it only with other areas you compute the same way, not with the tier cutoffs above.
If your service area is part of a metro rather than the whole of it, run the same division on the counties you actually serve. A metro average can hide a very different picture at the county line.
When does this index not apply?
When the question is whether a market is profitable, when your work does not depend on housing age, or when your service area is a small slice of a metro. The index measures competitive intensity against older housing. A large contractor field often marks a healthy market where homeowners spend freely, so a crowded tier is not a warning sign on its own.
- It is not spending. It counts older homes and contractor businesses. It does not observe what anyone spends on remodeling or repair.
- It is not advice to relocate. Moving a business involves licensing, labor, reputation, and cost of living, none of which the index measures.
- It leaves out new construction by design. Builders and trades that work mainly on new homes should read the density figure, not the index.
- It counts commercial contractors too. The contractor count includes specialty trade firms that work only on commercial buildings, while the housing count is homes only. Metros with a large commercial construction sector will look somewhat more crowded for residential work than they are.
- It cannot see contractors who never file. Businesses with no employees are counted from business tax returns, so operators paid in cash who never file are invisible. That makes every market look somewhat less crowded than it is, likely more so where informal work is common.
- Its data has a lag. Housing data covers 2020 to 2024, and contractor counts are from 2023, the latest year the Census Bureau has published.
How we measured this
Population. The 100 largest US metropolitan areas by population, excluding San Juan, Puerto Rico, for which comparable business data is not published.
What we count as demand. Owner-occupied homes built before 1980, from the Census Bureau’s American Community Survey (2020 to 2024 five year estimates). Older homes need more work, and owner-occupied homes are the ones whose owners pay for it. We use pre-1980 rather than “40 years and older” because the survey reports year built in decade buckets, and a 40 year cutoff falls inside one of them.
What we count as supply. Contractor establishments in NAICS 238, specialty trade contractors, combining employer establishments from County Business Patterns with businesses that have no employees, mostly sole proprietors, from Nonemployer Statistics, both 2023. Businesses with no employees are about three quarters of the field, so any measure that leaves them out describes a different market.
The metric. Pre-1980 owner-occupied homes divided by contractor establishments: how many older homes there are for each business able to work on them. It is an index built from housing stock, not a measure of observed remodeling spending.
How we tested it. We tried to break the index before publishing it. Moving the housing cutoff to 1970 or to 1990 left the ordering of metros almost unchanged (correlation 0.99 with the published index). Using 2022 contractor counts instead of 2023 gave above 0.99. Counting all housing units, rentals and vacant homes included, gave 0.98. The rough worker count described above gave 0.89. Weighting the housing count by household income gave 0.96, and by home value 0.82. Repeating the size check across all 924 metro and micropolitan areas is what showed the weak lean toward smaller markets, which is why the size finding is limited to the 100 largest. As an outside check, our Census pull matches the National Association of Home Builders’ 2024 figure for the median age of an owner-occupied home, 42 years.
Known limits. Demand data is 2024 and supply data is 2023, because no later supply year is published. Median value and income are survey estimates with margins of error, so small differences between neighboring metros are not meaningful. Supply counts all specialty trade contractors, including firms that work only on commercial buildings, while demand counts homes only, so metros with a large commercial construction sector look somewhat more crowded for residential work than they are. Operators who never file a business tax return are not counted, which makes every market look somewhat less crowded than it is. A high contractor count often marks a healthy, high spending market; this measures competitive intensity, not desirability.
Sources. US Census Bureau: American Community Survey five year estimates, County Business Patterns, Nonemployer Statistics. All public domain. The full index, method, and CSV are free to reuse under CC BY 4.0 with attribution to Capitol Data Analytics. Figures in this article are rounded to one decimal from the unrounded index, while the CSV carries two, so the two can differ by rounding: McAllen is 2.948, which appears as 2.95 in the CSV and 2.9 here.
Where to go from here
Where to compete is half of any expansion decision. The other half is what a customer costs once you are there, and our benchmark of what a booked home services job costs by channel covers that side. If you want the same clarity about your own shop before you spend on a new market, a free Profit Leak Audit measures what your current marketing returns per booked job, and the findings are yours to keep whether or not we work together.
Frequently Asked Questions
What is the least saturated market for contractors?
Among the 100 largest US metros, Buffalo, New York has the most older homes per contractor business: 50.2 owner-occupied homes built before 1980 for each specialty trade contractor. The least crowded quarter is mostly Northeastern and Midwestern metros, along with a few expensive coastal ones such as San Jose, San Francisco, and Honolulu.
Are fast growing cities good for starting a contracting business?
Not by this measure. We did not measure population growth, but Austin, Raleigh, Orlando, and Cape Coral, where fewer than one in four owner-occupied homes predates 1980, all sit in the most crowded tier. That describes competition for work on older homes, not whether a market is good for business overall.
How many contractors are there per home in the US?
It varies by 4.3 times across large metros. Counting businesses with no employees, Buffalo has 152 specialty trade contractor businesses per 10,000 owner-occupied homes, while Miami has 649. Nationally there were about 2.5 million such businesses in 2023, and 79% of them had no employees, most of them sole proprietors.
How do I tell if my market is oversaturated with contractors?
Divide your area’s owner-occupied homes built before 1980 by its specialty trade contractor businesses, including those with no employees. Among the 100 largest metros, a result below about 11 falls in the most crowded quarter and above about 23 in the least crowded. Every input is free from the Census Bureau, and CDA’s public index already has the number for each of the 100 largest metros.
What are the best metros to start an HVAC or plumbing business?
Our index covers all specialty trades together, and on that measure the least crowded large metros are older housing markets such as Buffalo, Pittsburgh, and Rochester. For a trade specific read, run the same division on plumbing, heating, and air conditioning contractors (NAICS 238220 in County Business Patterns, 23822 in Nonemployer Statistics) and compare it only with areas computed the same way. Least crowded is not automatically best.
Know what a customer costs you now
Where to compete is half the decision. A free Profit Leak Audit measures the other half: what your current marketing actually returns per booked job, read from your own CRM and ad data. The findings are yours to keep whether or not we work together.
Book a Profit Leak Audit